

Up to 30% of eligible investment
Maximum common premium
Composed of sub-bonuses including job creation, per Korte Law's 2026 grants guide to Law 03-22.
30% of the investment amount
Cap on cumulated premiums
Legal commentary on the Government Council position, with a separate 30 million MAD ceiling, approximately EUR 2.8 million, for renewable energy projects.
Above 50 million MAD excluding tax and 50 permanent jobs
Entry threshold, main mechanism
Practitioner guidance on eligibility; approximately EUR 4.6 million or USD 5.4 million at indicative 2026 exchange rates.
Land above 20% of total, study costs, working capital
Eligible base exclusions
These exclusions disproportionately reduce the qualifying base of store-led retail projects.
Morocco's Investment Charter (Law 03-22) excludes commercial and real estate activity from key provisions. How retail investors structure logistics, manufacturing and franchise assets to stay premium-eligible.
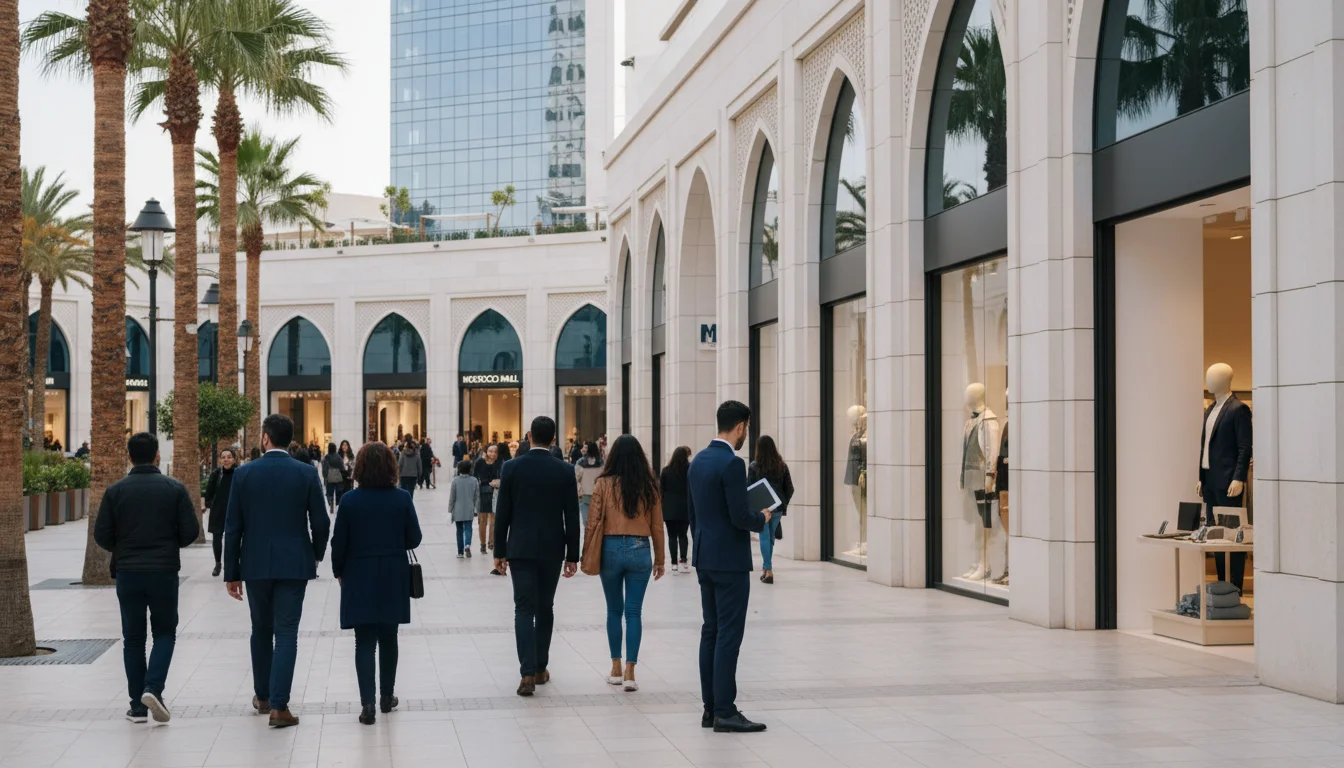
What changed: pure distribution sits outside the Charter's premium core
Direct answer: Morocco's Investment Charter, framework Law 03-22, was promulgated on 9 December 2022 and published in the Bulletin Officiel, replacing the 1995 charter's tax-exemption logic with cash premiums paid against verified milestones. It was made operational by Decree 2-23-1 and Head of Government decisions 3-12-23, 3-13-23 and 3-14-23.
For retail, the operative point in 2026 is that shelf-space distribution is not where the money is. Agricultural projects are expressly outside the framework law, while real estate and commercial sector investors are excluded from specific provisions of the Charter. Retail capital can still reach the support envelope of up to 30% of eligible investment, but only where spend is booked in an eligible activity: logistics and cold chain, light manufacturing or private label production, and industrially integrated franchise platforms.
- Agriculture is outside framework Law 03-22 entirely, while commercial and real estate investors are excluded from specific provisions of the Charter, so pure retail distribution is largely outside the premium core rather than outside Morocco's investment regime.
- The common premium can reach up to 30% of the eligible investment amount, and legal commentary on the Government Council position indicates total cumulated premiums are capped at 30%, making 30% the prudent modelling ceiling rather than the theoretical 55% stack.
- The eligible base excludes land costs above 20% of the total, preliminary study costs and working capital, which structurally penalises store-led retail capital expenditure.
- Practitioner guidance points to entry thresholds of more than 50 million MAD excluding tax, approximately EUR 4.6 million, plus at least 50 permanent jobs, which rules out most single-site retail formats.
- Where a project spans several sectors, only one sectoral premium applies, corresponding to the activity carrying the largest share of total investment, making entity design and capex allocation decisive for retail groups with industrial or logistics components.
Framework Law 03-22, promulgated 9 December 2022
Legal basis and timeline
Operationalised by Decree 2-23-1 on the main and strategic support mechanisms, plus Head of Government decisions 3-12-23, 3-13-23 and 3-14-23.
Who it affects: retail profiles, project sizes and sectors concerned
The exclusion is narrower than the headlines suggest, and that nuance decides eligibility. The framework law removes agriculture from its scope entirely, whereas commercial and real estate investors are described in official and multilateral summaries as excluded from specific provisions rather than from the law as a whole. In practice, a retail group is not barred from Morocco, from full foreign ownership, or from investor protections. What it risks losing is access to the premium mechanism for the portion of capital expenditure that is purely commercial: store fit-outs, retail leases, signage, point-of-sale equipment and working capital.
Four investor profiles are directly concerned.
- International grocery, DIY and specialty chains planning multi-store rollouts where the capital base is store-led rather than asset-led.
- Franchisees and master franchisees importing a brand system with limited local industrial content.
- Domestic distribution groups considering backward integration into packaging, assembly or food processing.
- Logistics and e-commerce fulfilment sponsors building warehousing, cold chain or last-mile platforms serving retail clients.
Project size matters as much as sector. Practitioner guidance indicates the main support mechanism targets companies incorporated under Moroccan law whose project exceeds 50 million MAD excluding tax and creates at least 50 permanent positions, roughly EUR 4.6 million or USD 5.4 million at indicative 2026 exchange rates. That threshold alone disqualifies most single-site or pilot retail formats, irrespective of the sector question. Below it, sponsors should look to the separate scheme for very small, small and medium enterprises, which the US State Department confirms has been published under the Charter. Nationality is not a filter: the Charter applies equally to foreign and domestic investors, with no local equity or technology transfer condition of eligibility, a position echoed by commentary on full foreign ownership across most sectors.
Detailed provisions: how the Charter's incentive architecture reads for retail-adjacent capital
The main support mechanism is built from stacked premiums rather than a single rate. The common premium can reach up to 30% of the eligible investment amount and is composed of sub-bonuses, including job creation, with further sub-bonuses linked to criteria such as female employment and local integration. A territorial premium of up to 15% targets less developed provinces, classified into categories A and B by Head of Government decision, and a sectoral premium rewards priority activities.
Two published figures diverge on the sectoral component and investors should treat this as a verification point rather than settled fact: consulting commentary cites a sectoral premium of up to 10% alongside a theoretical stacked maximum of 55% subject to caps in the implementing decrees, while contemporaneous reporting on the decree stated that sectoral premiums reach up to 5% of the eligible investment. Legal analysis of the Government Council's position is that total cumulated premiums cannot exceed 30% of the investment amount, with a 30 million MAD ceiling for renewable energy projects, approximately EUR 2.8 million. For modelling purposes, the disciplined assumption is a 30% cap on the eligible base, not 55%.
The eligible base is where retail structuring is won or lost. Land costs above 20% of the total, preliminary study costs and working capital needs are not covered by the grant. A store-heavy retail plan therefore presents a base dominated by non-qualifying items, while a logistics or production plan presents equipment, buildings and installed capacity. Premiums are also cash, not credits: they are disbursed against verified milestones under an investment agreement, separately from standard tax incentives.
Those standard incentives remain relevant even where premium access is limited. Reported measures include VAT exemption on investment goods for 36 months, professional tax exemption for five years, and reduced customs duties, described as 2.5% or nil. Where a project spans several activities, the Charter allows the sectoral premium only once, for the sector carrying the largest share of total investment, per published legal commentary on Law 03-22. For a mixed retail and industrial group, that rule makes the internal allocation of capital expenditure a deliberate structuring decision.
| Retail-linked structure | Likely posture under the Charter | Primary condition to verify |
|---|---|---|
| Multi-store rollout, own account | Commercial activity; excluded from specific premium provisions | Whether any capex is reclassifiable as industrial or logistics |
| Distribution centre, cold chain, fulfilment | Logistics platforms cited among eligible project types | Land share capped at 20% of the eligible base |
| Private label or light manufacturing unit | Industrial activity, premium-oriented | 50 million MAD and 50 permanent jobs thresholds |
| Franchise with local production or assembly | Eligibility follows the dominant activity, not the brand | Single sectoral premium applies to the largest investment share |
Action steps and next steps for retail investors in 2026
First, re-cut the capital expenditure schedule before filing anything. Separate commercial spend from industrial and logistics spend line by line, and test the eligible base against the exclusions for land above 20%, study costs and working capital. A plan that reaches the 50 million MAD threshold on paper may present a far smaller qualifying base once those deductions apply.
Second, choose the vehicle that matches the activity. Where a group operates both stores and a production or distribution platform, separate legal entities usually give cleaner eligibility, cleaner audit trails and cleaner treatment under the single sectoral premium rule. Our Financial Advisory and Structuring and Market Entry and Business Setup teams model this trade-off against tax, customs and governance consequences.
Third, price the territorial decision explicitly. Because the territorial premium is province-based, warehouse and plant siting is a financial decision as much as an operational one. Benchmark logistics cost against the premium uplift rather than assuming one offsets the other, and run the comparison in our investment simulator.
Fourth, engage the institutional channel early. Regional investment centers and the national investment promotion agency operate as entry points and publish sector and jurisdiction-level procedural information, as documented in the 2024 investment climate review. Investment agreements pass through the national and regional commissions established by decree.
Fifth, protect the exit. Registering the investment with the foreign exchange authority is what preserves repatriation rights, a point emphasised in practitioner guidance on Charter filings. Pair this with a compliance calendar for milestone verification, since premiums are disbursed only against evidenced delivery. Our Risk Management and Compliance practice builds that calendar into the shareholder reporting cycle.
Conclusion: eligibility follows the asset, not the brand
The Investment Charter does not penalise retail. It simply pays for industrial capacity, logistics capacity and regional rebalancing, and a store network delivers none of those on the eligible-base definition that governs the premium calculation. Sponsors who treat Law 03-22 as a retail subsidy will file and be disappointed. Sponsors who treat it as a capital expenditure classification exercise, and who build the Moroccan platform around production and distribution assets with retail as the downstream channel, retain access to the support architecture on its own terms.
Two caveats belong in every board paper. Published sources diverge on the sectoral premium calibration, and the exclusion applying to commercial activity is drafted against specific provisions rather than the entire Charter, so the applicable decree and decision texts must be read before committing capital.
To pressure-test a retail, franchise or logistics structure against current eligibility criteria, review our services or contact the Smart.by research desk. This note is informational and does not constitute financial, tax or legal advice.
Les informations fournies par Smart.by sur le site www.smartbyllc.com sont fournies à titre informatif uniquement et ne constituent pas un conseil financier. Veuillez nous contacter pour en savoir plus.
Analyses, actualités et ressources financières
Rejoignez plus de 300 abonnés.


Simplifier les décisions financières complexes grâce à la FAQ.
Un conseil en investissement de bout en bout : allocation de capital, évaluation des risques, fusions-acquisitions et optimisation d'actifs, ainsi qu'un accompagnement dédié aux investisseurs étrangers qui s'implantent au Maroc, incluant l'étude de marché, la navigation réglementaire et la mise en place opérationnelle. Chaque mission s'appuie sur Smart Flow, notre plateforme d'analyse d'investissement en temps réel.
Des investisseurs fortunés, des sociétés de private equity et de capital-risque, ainsi que des entreprises qui se développent au Maroc et en Afrique. Ce qu'ils ont en commun, c'est une préférence pour les données plutôt que pour les suppositions, et pour les résultats plutôt que pour les promesses rassurantes.
Réservez une consultation sur notre site, ou appelez-nous ou écrivez-nous directement. Nous relierons vos objectifs à un plan d'action dès ce premier échange, sans processus d'intégration interminable.
Votre investissement, visible en temps réel. Smart Flow suit l'avancement des projets, fait remonter les risques avant qu'ils ne deviennent un problème, et réunit le reporting financier et la collaboration d'équipe en un seul endroit, afin que vous n'ayez jamais à attendre une mise à jour trimestrielle pour savoir où vous en êtes.
Le tourisme, l'industrie manufacturière, l'agroalimentaire, le transport et la logistique, l'automobile et l'immobilier : des secteurs dans lesquels nous évoluons depuis assez longtemps pour repérer les risques et les opportunités que d'autres manquent.
Un capital déployé de manière délibérée, des risques gérés plutôt que découverts, et une entrée sur le marché qui ne s'enlise pas dans les formalités administratives. Nos clients mesurent le succès en rendements, pas en activité.
Chiffrées, à accès contrôlé, et auditées de manière indépendante et régulière. Vos données d'investissement bénéficient de la même rigueur que votre stratégie d'investissement.
Toujours. Nous gérons l'actif, pas seulement la transaction : suivi continu de la performance, gestion des risques et ajustements stratégiques au fil de l'évolution du marché.
Abonnez-vous à notre newsletter pour recevoir des analyses de marché et de nouvelles opportunités dès qu'elles se présentent, ou suivez-nous sur les réseaux sociaux pour des mises à jour en temps réel.
Elle est intégrée, pas ajoutée après coup. Nous pesons les facteurs environnementaux, sociaux et de gouvernance au même titre que les facteurs financiers, car la valeur à long terme et l'investissement responsable ne s'opposent pas.
Appelez le +212 6 41 52 96 83, ou rendez-nous visite à Tanger, Casablanca ou Marrakech. Vous pouvez également joindre notre équipe à tout moment via la page de contact.

Encore des questions avant de vous engager ?
- Parlez à un consultant, pas à un centre d'appels
- Consultez vos chiffres sur Smart Flow avant de décider