

~MAD 181,000 per year (~EUR 16,600)
Fully-loaded cost per bilingual IT support seat, Casablanca
Smart.by indicative 2026 estimate, equivalent to about MAD 15,100 per month per seat.
~MAD 114,000 and ~MAD 142,000 per year
Cairo and Tunis equivalents
Indicative estimates restated into MAD, placing Cairo about 37% and Tunis about 22% below Casablanca.
1.77x to 1.83x
Loading multiple on gross base salary
Indicative and strikingly stable across the three cities, implying base pay is only 55% to 60% of true seat cost.
~MAD 6,000
Annual attrition cost per seat, Casablanca
Indicative, based on a 30% churn rate and MAD 20,000 recruitment plus ramp-up cost per leaver.
Fully-loaded cost per bilingual IT support seat in 2026: an indicative MAD 181,000 per year in Casablanca versus Cairo and Tunis, covering wage bands, attrition, rent and effective tax.
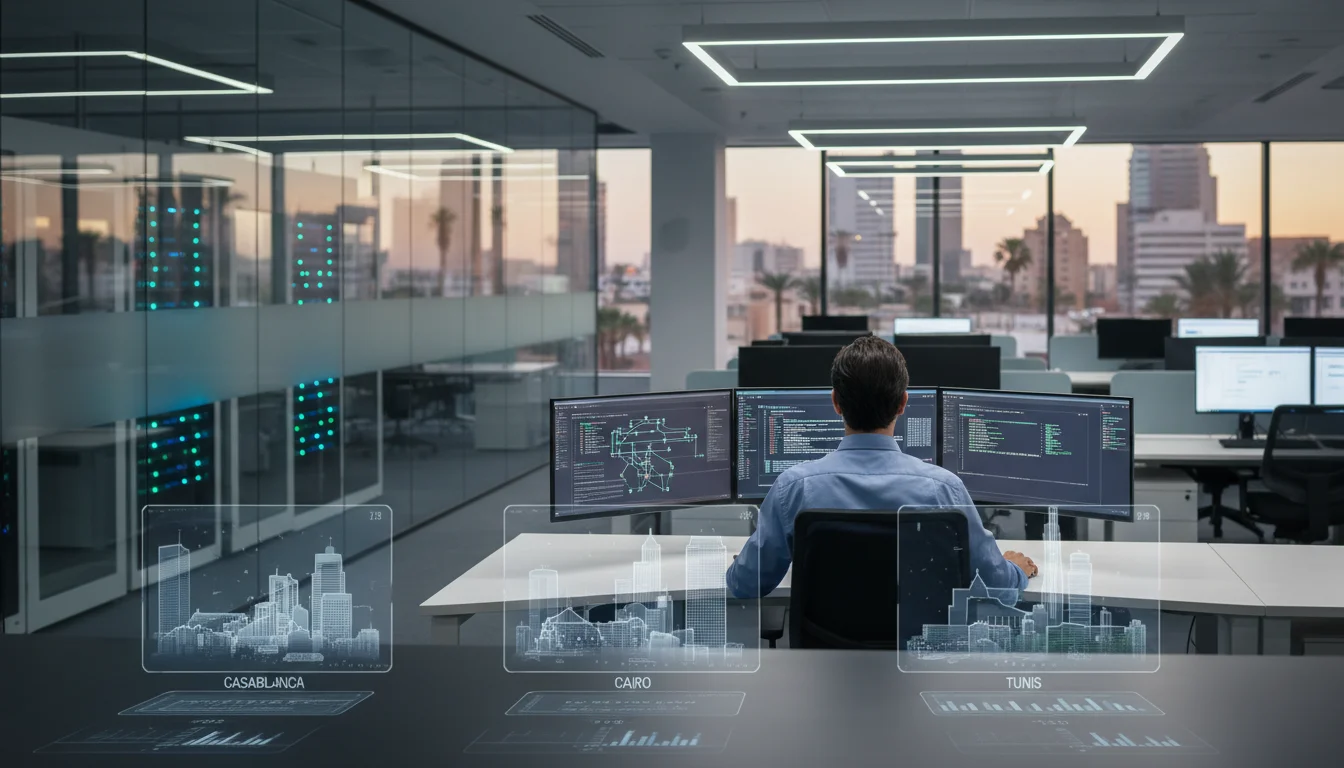
Key Metric: One Bilingual IT Support Seat in Casablanca Costs Roughly MAD 181,000 per Year
Direct answer: on our indicative 2026 model, one fully-loaded bilingual IT support seat in Casablanca costs approximately MAD 181,000 per year (about EUR 16,600 or USD 18,800), equivalent to roughly MAD 15,100 per month. The same seat models at roughly MAD 114,000 per year in Cairo (about EUR 10,500) and MAD 142,000 per year in Tunis (about EUR 13,000). Casablanca therefore prices at a premium of around 59% over Cairo and around 27% over Tunis on a like-for-like, French-plus-English, level-one support profile.
These figures are Smart.by research desk indicative estimates built from a transparent bottom-up structure rather than published survey data. They are not hard market prices and should be treated as a modelling baseline to be re-tested against live quotes, not as a quoted benchmark. Each city figure aggregates the same nine cost lines: gross base salary, employer social charges, allowances and shift premiums, recruitment and replacement cost driven by attrition, workstation occupancy cost, technology and connectivity, supervisory and quality overhead, training amortisation, and a small provision for local indirect taxes not recoverable on an export basis.
The single most important point for a capital allocator is structural: base salary explains only about 55% to 60% of the true cost of a bilingual IT support seat. The remaining 40% or so sits in charges, churn and occupancy, which is precisely where the three cities diverge most and where headline wage comparisons mislead. Investors modelling a nearshore build should therefore price the wedge, not the wage. Our investment simulator can be used to stress-test the same structure against your own assumptions.
- Indicative 2026 fully-loaded cost per bilingual IT support seat: approximately MAD 181,000 per year in Casablanca (~EUR 16,600), MAD 142,000 in Tunis and MAD 114,000 in Cairo.
- Gross base salary explains only about 55% to 60% of true seat cost; the loading multiple is a stable 1.77x to 1.83x across all three cities.
- Attrition is a cash line, not a KPI: at 30% churn and MAD 20,000 per replacement, Casablanca carries roughly MAD 6,000 per seat per year in churn cost.
- Occupancy is only 5% to 6% of seat cost, so the seat-sharing ratio across shifts matters more than negotiated rent per square metre.
- Cairo's nominal 37% discount to Casablanca is partly a currency translation effect and should be modelled as reversible; Morocco's premium buys euro-cost predictability.
MAD 3.5m to 5.5m capex against MAD 18.1m annual run-rate
100-seat build, Casablanca
Indicative scenario showing that working capital, not capex, is the principal financing constraint.
Casablanca, Cairo and Tunis Benchmark: A Line-by-Line Cost Per Seat Comparison
The table below sets out the full benchmark structure. All values are indicative estimates for calendar 2026, expressed in Moroccan dirham with euro approximations, and converted at illustrative reference rates of EUR 1 = MAD 10.9 and USD 1 = MAD 9.6. Non-Moroccan local currency amounts have been restated into MAD for comparability, which means Cairo and Tunis figures carry additional foreign exchange translation risk that Casablanca figures do not.
| Cost line (per seat, 2026 indicative) | Casablanca | Cairo | Tunis |
|---|---|---|---|
| Gross monthly base salary, bilingual L1 agent | MAD 8,500 (~EUR 780) | MAD 5,200 equiv. (~EUR 480) | MAD 6,600 equiv. (~EUR 605) |
| Employer social charges, % of gross (ceilings apply) | ~20% | ~19% | ~17% |
| Allowances, transport, meal, shift and night premiums | ~10% of base | ~12% of base | ~10% of base |
| Annual voluntary attrition band | 25% to 35% | 35% to 45% | 25% to 35% |
| Replacement cost per leaver (hiring plus ramp-up) | MAD 20,000 | MAD 13,000 equiv. | MAD 16,000 equiv. |
| Occupancy cost per seat per year, offshoring-park grade | MAD 10,100 | MAD 7,000 equiv. | MAD 8,000 equiv. |
| Technology, connectivity and licences per year | MAD 12,000 | MAD 11,000 equiv. | MAD 11,500 equiv. |
| Supervisory, QA and training overhead | ~15% of direct people cost | ~15% | ~15% |
| Fully-loaded annual cost per seat | MAD 181,000 (~EUR 16,600) | MAD 114,000 (~EUR 10,500) | MAD 142,000 (~EUR 13,000) |
| Implied loading multiple on base salary | 1.77x | 1.83x | 1.79x |
Three observations follow from the comparison. First, the loading multiple is remarkably stable across all three cities, between roughly 1.77x and 1.83x gross base pay. That stability is useful: it means an investor who can source a reliable local wage band can approximate a fully-loaded cost per bilingual IT support seat with reasonable confidence before commissioning detailed diligence.
Second, Cairo's nominal advantage is real but it is the most volatile of the three. A large share of the gap is a translation effect rather than a productivity effect, and local wage re-pricing in high-inflation conditions can compress the arbitrage within a single contract cycle. Second-order costs also work against Cairo in this model: the higher attrition band adds proportionally more replacement cost per productive seat, which is why its loading multiple is the highest of the three.
Third, Tunis occupies a genuine middle position. It typically offers the deepest native French capability per thousand candidates of the three markets, with employer social charges modelling slightly lower than Casablanca, but it has a thinner pool for high-volume English-plus-French dual staffing and an emigration-driven churn profile that is structural rather than cyclical.
On effective tax, the comparison is deliberately hedged here. Each of the three jurisdictions applies a standard corporate income tax rate alongside preferential regimes for exported services, and Morocco has been running a multi-year convergence of its corporate income tax rates with a distinct treatment for exporters and for companies established in designated financial and industrial acceleration zones. Because we could not ground the exact 2026 rates in a primary source for this note, treat any specific percentage as requiring confirmation with the applicable tax administration and your advisers. The structural point stands regardless of the decimal: for a labour-intensive support centre, the employer payroll wedge and the recoverability of indirect tax on inputs usually move fully-loaded cost per seat more than the headline corporate rate does, because taxable profit is small relative to payroll.
Interpretation: What Actually Drives the Gap Between the Three Cities
The cost gap is driven by four mechanics, in descending order of materiality.
1. Language scarcity premium. A dual French and English profile with a technical baseline is a narrower pool than either language alone. Casablanca prices that scarcity most visibly because it competes for the same candidates with banking, insurance, shared service centres and established offshoring operators, all recruiting from a broadly similar graduate cohort. Where an operator can accept French-only or English-only delivery, the wage band for the same seat compresses materially, and the Casablanca premium narrows.
2. Attrition as a cost, not a KPI. Attrition converts directly into cash. At a 30% annual churn rate and a replacement cost of MAD 20,000 per leaver, Casablanca carries roughly MAD 6,000 per seat per year in pure churn cost, before counting the quality and service-level penalties that arrive with a permanently junior bench. Every 5 percentage points of attrition avoided is worth approximately MAD 1,000 per seat per year in this model, and considerably more once ramp-up inefficiency is priced. This is the line item most responsive to management action, and therefore the one that separates a well-run centre from a poorly run one in the same city.
3. Occupancy and shift design. Occupancy is the smallest of the big four lines, at roughly 5% to 6% of fully-loaded cost per seat in all three cities. The lever is not the rent per square metre but the seat-sharing ratio: a centre running genuine two-shift coverage halves the effective real estate cost per full-time equivalent. Investors who negotiate hard on rent while accepting single-shift utilisation are optimising the wrong variable.
4. Currency and regime stability. Morocco's managed exchange arrangement has historically produced less violent translation swings than Egypt has experienced, which matters to a euro-billing client on a three-year contract. Stability is an economic good, and part of the Casablanca premium is a rational payment for it rather than an inefficiency to be arbitraged away.
Investment Implications: Financing a 100-Seat Build and Structuring the Arbitrage
Translated into a deal, the benchmark implies the following indicative economics for a 100-seat bilingual delivery centre.
| 100-seat centre, indicative 2026 | Casablanca | Cairo | Tunis |
|---|---|---|---|
| Annual operating run-rate | MAD 18.1m (~EUR 1.66m) | MAD 11.4m (~EUR 1.05m) | MAD 14.2m (~EUR 1.30m) |
| Fit-out and IT capex per seat | MAD 35,000 to 55,000 | MAD 30,000 to 50,000 | MAD 32,000 to 52,000 |
| Total start-up capex, 100 seats | MAD 3.5m to 5.5m | MAD 3.0m to 5.0m | MAD 3.2m to 5.2m |
| Break-even cost per productive hour (1,700 hrs/FTE) | MAD 106 (~EUR 9.7) | MAD 67 (~EUR 6.2) | MAD 84 (~EUR 7.7) |
Four implications for investors and their finance teams.
Working capital dominates the first year. Capex of MAD 3.5m to 5.5m is modest next to an MAD 18.1m annual run-rate. The binding constraint is the cash gap between payroll, which is monthly and non-negotiable, and client receivables of 45 to 90 days, compounded by a ramp period in which billable utilisation sits well below steady state. A defensible model funds roughly four to six months of fully-loaded cost per bilingual IT support seat as working capital, not two. Structuring that facility correctly is a financial advisory and structuring question before it is an operational one.
Contract currency is the real risk allocation. A euro-denominated revenue line against a dirham cost base creates a structural long-euro position. Investors should decide explicitly whether that exposure is hedged, passed to the client through an indexation clause, or retained as an intentional position. In Cairo, the same analysis is materially more consequential, because the apparent 37% cost advantage is partly a currency artefact that local wage inflation tends to reclaim over time.
Incentive regimes should be modelled as contingent, not guaranteed. Morocco offers preferential frameworks for exported services and for companies located in designated zones, and regional investment centres administer support instruments tied to job creation and investment thresholds. Any specific rate or grant amount must be verified against the applicable regulator and the current finance law before it is underwritten. Prudent practice is to model the base case without incentives and treat any benefit as upside, an approach that sits naturally with disciplined risk management and compliance work.
Site selection should be scored, not assumed. If the mandate is lowest nominal cost per bilingual IT support seat, Cairo wins on this model. If the mandate is euro-cost predictability, regulatory familiarity for European clients and same-time-zone proximity, Casablanca justifies its premium. Tunis is the balanced choice for French-dominant workloads at moderate scale. Framing that decision properly is the purpose of structured market research and intelligence and, once a location is chosen, disciplined market entry and business setup execution.
Conclusion: Price the Wedge, Then Verify Locally
The headline of this benchmark is not that Casablanca is expensive. It is that the fully-loaded cost per bilingual IT support seat runs at approximately 1.8 times gross base salary in all three cities, so the investment case is decided by attrition management, shift design and contract currency rather than by wage shopping. On our indicative 2026 model, that produces roughly MAD 181,000 per seat per year in Casablanca, MAD 142,000 in Tunis and MAD 114,000 in Cairo, with Morocco buying stability and proximity for the difference.
Every figure in this note is an indicative estimate published for analytical framing, not a quoted price or financial advice, and wage bands, rents and tax treatment must be confirmed locally before capital is committed. If you are sizing a delivery centre, pressure-test these assumptions against your own volumes and service levels using our investment simulator, review the wider service range, or contact the Smart.by research desk for a site-specific cost model.
Les informations fournies par Smart.by sur le site www.smartbyllc.com sont fournies à titre informatif uniquement et ne constituent pas un conseil financier. Veuillez nous contacter pour en savoir plus.
Analyses, actualités et ressources financières
Rejoignez plus de 300 abonnés.


Simplifier les décisions financières complexes grâce à la FAQ.
Un conseil en investissement de bout en bout : allocation de capital, évaluation des risques, fusions-acquisitions et optimisation d'actifs, ainsi qu'un accompagnement dédié aux investisseurs étrangers qui s'implantent au Maroc, incluant l'étude de marché, la navigation réglementaire et la mise en place opérationnelle. Chaque mission s'appuie sur Smart Flow, notre plateforme d'analyse d'investissement en temps réel.
Des investisseurs fortunés, des sociétés de private equity et de capital-risque, ainsi que des entreprises qui se développent au Maroc et en Afrique. Ce qu'ils ont en commun, c'est une préférence pour les données plutôt que pour les suppositions, et pour les résultats plutôt que pour les promesses rassurantes.
Réservez une consultation sur notre site, ou appelez-nous ou écrivez-nous directement. Nous relierons vos objectifs à un plan d'action dès ce premier échange, sans processus d'intégration interminable.
Votre investissement, visible en temps réel. Smart Flow suit l'avancement des projets, fait remonter les risques avant qu'ils ne deviennent un problème, et réunit le reporting financier et la collaboration d'équipe en un seul endroit, afin que vous n'ayez jamais à attendre une mise à jour trimestrielle pour savoir où vous en êtes.
Le tourisme, l'industrie manufacturière, l'agroalimentaire, le transport et la logistique, l'automobile et l'immobilier : des secteurs dans lesquels nous évoluons depuis assez longtemps pour repérer les risques et les opportunités que d'autres manquent.
Un capital déployé de manière délibérée, des risques gérés plutôt que découverts, et une entrée sur le marché qui ne s'enlise pas dans les formalités administratives. Nos clients mesurent le succès en rendements, pas en activité.
Chiffrées, à accès contrôlé, et auditées de manière indépendante et régulière. Vos données d'investissement bénéficient de la même rigueur que votre stratégie d'investissement.
Toujours. Nous gérons l'actif, pas seulement la transaction : suivi continu de la performance, gestion des risques et ajustements stratégiques au fil de l'évolution du marché.
Abonnez-vous à notre newsletter pour recevoir des analyses de marché et de nouvelles opportunités dès qu'elles se présentent, ou suivez-nous sur les réseaux sociaux pour des mises à jour en temps réel.
Elle est intégrée, pas ajoutée après coup. Nous pesons les facteurs environnementaux, sociaux et de gouvernance au même titre que les facteurs financiers, car la valeur à long terme et l'investissement responsable ne s'opposent pas.
Appelez le +212 6 41 52 96 83, ou rendez-nous visite à Tanger, Casablanca ou Marrakech. Vous pouvez également joindre notre équipe à tout moment via la page de contact.

Encore des questions avant de vous engager ?
- Parlez à un consultant, pas à un centre d'appels
- Consultez vos chiffres sur Smart Flow avant de décider