

Approx. 3.7% (approx. 3% per a second source)
CBAM-covered share of Morocco's exports to the EU
Transitional-phase data, mainly fertilisers and, to a lesser extent, cement; scope extension to automotive, textiles and agri-food would raise exposure toward roughly 10%.
2.5% in 2026, 48.5% in 2030, 100% by 2034
Certificate coverage factor
Free-allocation adjustment means only a fraction of embedded emissions requires certificates in 2026, so current cash cost understates the compounding liability.
EUR 75.36 (Q1) and EUR 75.28 (Q2), about MAD 813 per tCO2e
2026 CBAM certificate price
Quarterly averages apply to 2026 imports; weekly EU ETS auction averages apply from 2027.
19% by value, ahead of Russia at 12.8%
Morocco's position in EU fertiliser imports
By 2025 Morocco had become the EU's largest external fertiliser supplier, backed by approximately 68% of world proven phosphate rock reserves.
CBAM's definitive phase began January 2026. How Morocco's fertiliser, steel and aluminium exports to the EU reprice, and where captive-renewables capex pays off.
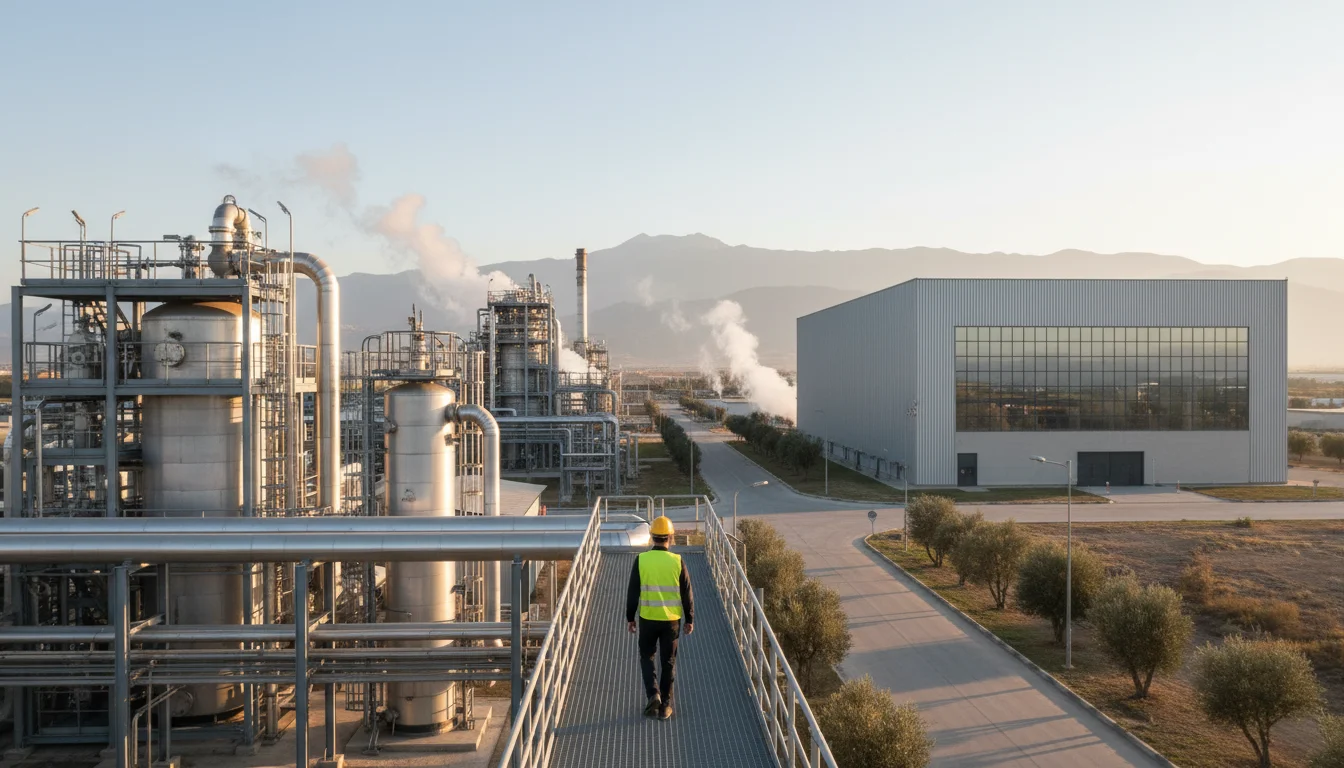
Executive summary: what CBAM's definitive phase changes for Moroccan industrial assets
Direct answer: the EU Carbon Border Adjustment Mechanism moved from reporting to payment on 1 January 2026, and the practical consequence for Morocco is that verified emissions data, not tariff schedules, now sets the landed cost of fertiliser, steel, aluminium and cement shipments into the European Union. The definitive regime, under which importers must buy and surrender CBAM certificates, started on 1 January 2026, but certificate sales were postponed to 1 February 2027, with declarants acquiring certificates in 2027 for 2026 imports and obligations applying retroactively. The first annual declaration and surrender fall due by 30 September 2027.
That two-stage design creates a narrow and unusually well-signposted window. The 2026 cash cost is small because the free-allocation adjustment means only 2.5% of embedded emissions require certificate coverage in 2026, rising to 48.5% in 2030 and 100% by 2034. The liability therefore compounds on a known schedule while the mitigation levers, captive renewables, process electrification, verified emissions accounting and product-mix reallocation, take two to four years to install.
For capital allocators the investable thesis is not the carbon bill itself. It is the spread that opens between Moroccan assets that can document a low emissions intensity and those that will be assessed on punitive default values. Every 0.1 tCO2e per tonne of emissions intensity is estimated to move cost by roughly EUR 9 per tonne (about MAD 97 at an indicative MAD 10.8 per EUR), which is enough to reorder supplier rankings in commoditised segments. Morocco's exposure is modest in aggregate but concentrated in exactly the assets that anchor its industrial export base.
- CBAM's definitive phase began 1 January 2026, but certificate sales open only on 1 February 2027, with the first declaration and surrender for 2026 imports due by 30 September 2027.
- Morocco's exposure is contained at roughly 3% to 3.7% of exports to the EU on transitional-phase data, concentrated in fertilisers and, to a lesser degree, cement; a scope extension to automotive, textiles and agri-food would raise it toward about 10%.
- The cost escalates on a published schedule: only 2.5% of embedded emissions require certificate coverage in 2026, rising to 48.5% in 2030 and 100% by 2034, so 2026 cash cost understates the obligation.
- Verified facility-level data is the decisive variable, since default values carry mark-ups of 10% in 2026, 20% in 2027 and 30% from 2028, and buyers cannot use actual values without accredited verification.
- Morocco's relatively low reported grid carbon intensity plus captive renewables is the primary mitigation lever, but the competitive gain is contingent on converting that energy profile into audited numbers an EU declarant will accept.
10% (2026), 20% (2027), 30% (from 2028); EUR 300 to EUR 500 per tCO2e penalty
Default-value mark-up and non-compliance penalty
Penalty applies to importing without authorisation, roughly MAD 3,240 to MAD 5,400 per tonne at indicative exchange rates.
Market size and growth trajectory: sizing Morocco's CBAM-exposed export market
Morocco is not among the most CBAM-exposed economies, and that is the starting point for any honest sizing. Transitional-phase data indicate that CBAM-covered products represent approximately 3.7% of Morocco's exports to the EU, mainly fertilisers and, to a lesser extent, cement. A separate assessment relayed by the Moroccan Exporters Confederation puts current coverage near 3% of exports, primarily fertilisers, and notes that a planned extension to automotive, textile and agri-food would lift total exposure toward roughly 10%. Two independent sources converging on a 3% to 4% current figure is the single most useful anchor in this file: the near-term carbon bill is manageable, the scope risk is not.
At product level, one policy assessment sizes the covered share at around 13% of fertiliser exports, equivalent to USD 455 million, and about 19% of cement exports, or USD 12.12 million, while projected hydrogen volumes would be fully covered. Converted at indicative rates, the fertiliser figure is roughly MAD 4.5 billion (about EUR 420 million) and the cement figure roughly MAD 120 million. These are the exposed revenue lines against which certificate cost should be measured, not total exports.
The growth driver is structural. Morocco holds approximately 68% of the world's proven phosphate rock reserves, and by 2025 it had overtaken Russia to become the EU's single largest fertiliser supplier, capturing 19% of total EU fertiliser imports by value against Russia's 12.8%. Market share gained on geopolitical realignment is now being tested on carbon intensity. Steel is the second front: Moroccan steel producers have been described as standing at a major European crossroads as the mechanism takes effect.
The cost trajectory below is illustrative. It holds the carbon price constant and applies the published CBAM factors to a blast-furnace steel reference, using benchmark figures already in the public record rather than company-specific data.
| Compliance year | Share of embedded emissions requiring certificates | Illustrative cost per tonne, BF steel reference | MAD equivalent (indicative) |
|---|---|---|---|
| 2026 | 2.5% | EUR 2.76 | MAD 30 |
| 2030 | 48.5% | EUR 53.5 | MAD 578 |
| 2034 | 100% | EUR 110.29 | MAD 1,191 |
Basis: a blast-furnace steel reference nets roughly EUR 2.76 per tonne in 2026 at the second-quarter price, against a gross EUR 110.29 at full coverage. The 2030 line is our own arithmetic on the published 48.5% factor and should be read as indicative, not as a forecast of carbon prices. For 2026 imports the Commission applies quarterly prices, published at EUR 75.36 for the first quarter and EUR 75.28 for the second, roughly MAD 813 per tonne of CO2 equivalent.
Regulatory and incentive framework: charter support, industrial zones and the carbon-data mandate
Two regulatory stacks now govern the same investment decision: the EU compliance stack, which sets the cost, and the Moroccan incentive stack, which sets how much of the mitigation capex the investor actually funds.
On the EU side, the mechanics are settled enough to underwrite. Obligations attach to authorised declarants importing above a mass threshold of currently 50 tonnes of CBAM goods per year, adjusted for ETS free allocation, with the first surrender deadline on 30 September 2027. Importers may report verified actual values or Commission default values, and verification by an accredited verifier is required only where actual values are used. Defaults carry mark-ups of 10% in 2026, 20% in 2027 and 30% from 2028, and accredited verifiers could register in the CBAM Registry from 1 September 2026. The commercial reading is blunt: an exporter without audited facility data is priced as if it were among the dirtiest producers in its class.
There is also a credit mechanism worth tracking. A declaration reduces by any carbon price effectively paid in the country of production under Article 9, but the implementing regulation recognising third-country carbon prices remained pending, with its consultation closed on 10 June 2026. From 2027 the Commission is expected to publish default carbon-price references for third-country regimes, enabling deduction of prices already paid abroad. Any Moroccan domestic carbon-pricing instrument therefore has direct balance-sheet relevance for exporters, which is why the mechanism has been characterised as an external audit of Morocco's climate readiness, shifting attention to whether factories can measure, verify and report emissions to European standards.
On the Moroccan side, investors should work through three channels rather than assume a single carbon-specific scheme exists. First, the national investment charter's support framework, which combines a common premium with additional premiums tied to territorial, sectoral and sustainability-related criteria; the exact eligibility grid and rates should be confirmed case by case with the applicable regional investment commission and the national investment promotion agency rather than assumed from published summaries. Second, industrial acceleration and export-oriented zones, which layer customs and tax treatment onto export platforms and remain the default vehicle for EU-facing manufacturing. Third, the electricity self-generation and renewable access framework, which is the operative lever for captive solar and wind behind the meter. A national CBAM workshop held on 5 February 2026 framed the shift as a simultaneously technical, economic and institutional challenge requiring coordination between the State, the private sector and international partners, which is a fair description of where the incentive architecture currently stands. Structuring advice on stacking these channels sits within financial advisory and structuring.
Regional financial benchmarking: Morocco against Egypt and Türkiye on carbon cost and capital
CBAM is a relative mechanism. An exporter does not compete against the carbon price; it competes against the emissions intensity of whoever else can ship into the same EU buyer. That makes regional benchmarking the core of the financial case.
Morocco's structural advantage is electricity. One sector assessment puts the national grid emission factor at roughly 0.48 to 0.55 kgCO2 per kWh, below EU default assumptions applied to countries without verified data, and notes that using actual grid data reduces Scope 2 calculations and therefore certificate cost; that figure comes from a single commercial source and should be treated as indicative until confirmed against the operator's published factor. The same source indicates that Morocco's aluminium sector faces a tariff-equivalent of around 23% under EU default values, which actual emissions data can substantially reduce. Again, single-source, but directionally consistent with the 10% to 30% default mark-ups in the regulation.
Egypt and Türkiye are the relevant comparators. Egypt and Algeria are described as especially exposed through fertiliser and other covered exports, while Tunisia, Morocco and several Gulf economies are exposed through fertilisers, cement, steel, aluminium and close EU trade links. Türkiye's proximity to EU buyers and its heavier steel complex make it the more demanding competitor in iron and steel, and it has been moving toward a domestic emissions-trading framework; investors should verify the current status of that framework directly with the applicable sector regulator before pricing any Article 9 deduction into a model.
| Indicator (indicative, for orientation) | Morocco | Egypt | Türkiye |
|---|---|---|---|
| Principal CBAM-exposed lines | Fertilisers, cement, steel, aluminium; future hydrogen | Fertilisers and other covered industrial exports | Iron and steel, cement, aluminium |
| Share of exports to EU covered | Approx. 3% to 3.7%, per transitional-phase data | Higher exposure cited for fertiliser-led trade | Material exposure via steel-led EU trade |
| Grid decarbonisation as a lever | Strong: low reported grid factor plus captive renewables | Moderate | Moderate |
| Domestic carbon price creditable under Article 9 | To be confirmed; no explicit price assumed here | To be confirmed | Framework in development; verify status |
| Dominant near-term risk | Default-value pricing from data gaps | Volume concentration in fertilisers | Steel emissions intensity |
Read together, the benchmark points to a specific financial conclusion. Morocco's competitive gain from CBAM is contingent, not automatic: it materialises only where an asset converts a genuinely low-carbon energy profile into audited numbers accepted by an EU declarant. Mid-sized exporters in aluminium and cement may face proportionally larger impacts relative to their compliance budgets than the largest fertiliser exporter, which has both the greatest absolute exposure and the resources to invest in compliance infrastructure. That asymmetry is where minority-stake and platform consolidation opportunities sit. Quantifying it per asset is the work covered by market research and intelligence.
Entry strategies and opportunities across the CBAM value chain
Four entry routes follow from the analysis above, ordered by capital intensity.
1. Verification and carbon-data infrastructure. The compliance gap is the least capital-intensive opportunity and the most immediate. Verifiers must perform on-site inspections in the first reporting year, 2026, with limited flexibility for virtual visits thereafter on a risk-based approach. Accredited verification capacity, monitoring instrumentation and plant-level data systems are services Moroccan exporters must buy, and that market did not exist at scale two years ago.
2. Captive renewables and self-generation. Where electricity is a material share of embedded emissions, notably in aluminium, downstream steel processing and fertiliser-adjacent operations, behind-the-meter solar, wind and storage convert a recurring regulatory cost into a depreciable asset. The investment test is straightforward: compare levelised cost of captive generation against the escalating certificate coverage schedule, not against today's 2.5% coverage. Modelling that crossover under different carbon-price paths is what the investment simulator and investment strategy and planning work are for.
3. Acquiring or partnering with low-carbon industrial assets. Assets with electric-route production, high renewable supply share and existing measurement discipline should trade at a premium to peers assessed on defaults. Conversely, otherwise sound assets currently penalised for data gaps are the classic remediable-discount target: the fix is process and audit capability, not a new furnace. Structuring, diligence and valuation support here falls under asset and portfolio management and the pipeline visible through deals and projects.
4. Export-platform establishment. For manufacturers relocating EU-facing production, Morocco offers proximity, established industrial zones and a favourable power profile. The counterweight is that market access is being renegotiated through regulation rather than tariffs: recent reporting has highlighted friction between Rabat and Brussels over a series of European rules affecting ports, banking, automotive and offshoring, which argues for entry structures that do not depend on a single regulatory assumption holding for a decade. Setting up the vehicle, permits and compliance perimeter is addressed through market entry and business setup and risk management and compliance. Across all four routes, the recommended sequence is the same: measure first, then abate, then commit capex.
Key risks and mitigation
Regulatory risk. Scope is the dominant variable. An extension to automotive, textile and agri-food would move Morocco's exposure from roughly 3% of exports toward approximately 10%, which would touch the country's largest manufacturing employers rather than a handful of heavy-industry sites. Mitigation: build emissions accounting in currently uncovered sectors before it is mandatory, and model a scope-extension scenario in any five-year plan.
Financial risk. The 2026 bill understates the obligation. Coverage rises from 2.5% to 48.5% in 2030 and 100% by 2034, and from 2027 declarants must hold certificates equal to at least 50% of cumulative embedded emissions at each quarter-end, reduced from a previously planned 80%. That is a working-capital charge that lands on the EU buyer and gets negotiated back into supply contracts. Mitigation: provision now, and renegotiate pass-through clauses before the first surrender cycle.
Operational risk. Data failure is the expensive failure mode. Where emissions are not audited by an accredited verifier, EU buyers cannot declare actual values and must apply Commission default values, raising liability and eroding competitiveness. Mitigation: treat verification readiness as a market-access condition with a hard internal deadline.
Market and counterparty risk. Importing without authorisation attracts penalties of EUR 300 to EUR 500 per tonne of CO2 equivalent, roughly MAD 3,240 to MAD 5,400, so Moroccan exporters should verify their EU counterparty's authorised-declarant status rather than assume it. There is also a broader political dimension: Europe's green trade restrictions have provoked resentment among lower-income exporting countries, which makes contested implementation and diplomatic pushback a live scenario rather than a tail risk.
Outlook to 2029: from compliance cost to competitive spread
The next three years are unusually legible because the calendar is fixed. Certificate sales open on 1 February 2027, and authorised declarants must submit the 2026 declaration and surrender certificates by 30 September 2027. From 2027 onwards the certificate price will follow the weekly average of EU ETS auction prices rather than the quarterly averages used for 2026 imports. Practically, 2027 is the first year in which Moroccan exporters receive priced, audited feedback on their carbon position, and the first year in which EU buyers can rank suppliers on verified cost rather than estimates.
Three developments are worth watching through 2029. First, adoption of the implementing regulation on recognising third-country carbon prices, which would determine whether any Moroccan domestic instrument reduces exporters' EU liability. Second, the scope decision on automotive, textiles and agri-food, the single largest swing factor for national exposure. Third, the pricing of hydrogen and ammonia derivatives; projected Moroccan hydrogen volumes are intended for the EU market and would be fully covered, which makes low-carbon certification a precondition for that export thesis rather than a bonus.
Our base expectation is a widening two-tier market. Assets combining renewable supply, electrified process routes and audited data should capture share from higher-intensity origins as the coverage factor climbs toward 48.5% by 2030, while undocumented producers absorb default mark-ups that rise to 30% from 2028. Because the mechanism prices emissions from imported iron and steel, aluminium, fertilisers, hydrogen and electricity, the winners will be defined at facility level, not country level. Investors should therefore underwrite plants, not jurisdictions.
Conclusion and next steps
CBAM has converted an environmental policy into an industrial cost curve with a published slope. For Morocco the aggregate exposure is contained, close to 3% to 4% of exports to the EU on transitional-phase data, but it is concentrated in the fertiliser complex that recently became the EU's largest external supplier, alongside steel, aluminium and cement operations facing the same measurement obligation with smaller compliance budgets. The 2026 cash cost is trivial at 2.5% coverage. The 2030 cost at 48.5% coverage is not, and the capex that reduces it has a multi-year lead time.
The disciplined response is sequential and unglamorous: establish verified facility-level emissions data, quantify the gap between actual and default-value pricing, then decide whether captive renewables, process change, product-mix reallocation or contractual pass-through delivers the better return per MAD deployed. Each of those steps is measurable, and none of them should be taken on assumed figures.
Smart.by's research desk works with international and local investors on exactly this sequence: sizing carbon-cost exposure at asset level, stress-testing mitigation capex against the published coverage schedule, and structuring entry or acquisition around verified rather than assumed data. To discuss a specific asset, portfolio or entry plan, review our services, test scenarios in the investment simulator, or contact the team. Further sector notes are published in our resources library. This note is informational and does not constitute financial advice.
La información proporcionada por Smart.by en el sitio www.smartbyllc.com tiene fines exclusivamente informativos y no constituye asesoramiento financiero. Contáctenos para obtener más información.
Análisis, noticias y recursos financieros
Más de 300 suscriptores confían en nosotros.


Simplificando decisiones financieras complejas a través de preguntas frecuentes.
Asesoramiento de inversión integral: asignación de capital, evaluación de riesgos, fusiones y adquisiciones, y optimización de activos, además de apoyo dedicado para inversionistas extranjeros que ingresan a Marruecos, incluyendo estudios de mercado, orientación normativa y puesta en marcha operativa. Cada proyecto se respalda con Smart Flow, nuestra plataforma de análisis de inversión en tiempo real.
Inversionistas de alto patrimonio, firmas de capital privado y de riesgo, y corporaciones que se expanden hacia Marruecos y África. Lo que todos ellos comparten es una preferencia por los datos frente a las conjeturas, y por los resultados frente a las promesas tranquilizadoras.
Reserve una consulta a través de nuestro sitio web, o llámenos o escríbanos directamente. En esa primera conversación, alinearemos sus objetivos con un plan de acción, sin necesidad de un proceso de incorporación prolongado.
Su inversión, visible en tiempo real. Smart Flow hace seguimiento del avance de los proyectos, detecta los riesgos antes de que se conviertan en un problema, y reúne el reporte financiero y la colaboración del equipo en un solo lugar, para que nunca tenga que esperar un informe trimestral para saber cómo van las cosas.
Turismo, manufactura industrial, agroindustria, transporte y logística, automotriz, e inmobiliario: sectores en los que llevamos el tiempo suficiente para detectar los riesgos y las oportunidades que otros pasan por alto.
Un capital invertido de manera deliberada, riesgos gestionados en lugar de descubiertos, y una entrada al mercado que no se estanca en trámites administrativos. Nuestros clientes miden el éxito en rendimientos, no en actividad.
Cifrados, con acceso controlado y auditados de forma independiente y periódica. Sus datos de inversión reciben el mismo rigor que su estrategia de inversión.
Siempre. Gestionamos el activo, no solo la operación: monitoreo continuo del desempeño, gestión de riesgos y ajustes estratégicos a medida que el mercado evoluciona.
Suscríbase a nuestro boletín informativo para recibir análisis de mercado y nuevas oportunidades apenas surjan, o síganos en redes sociales para actualizaciones en tiempo real.
Está integrada, no añadida después. Consideramos los factores ambientales, sociales y de gobernanza junto con los financieros, porque el valor a largo plazo y la inversión responsable no compiten entre sí.
Llame al +212 6 41 52 96 83, o visítenos en Tánger, Casablanca o Marrakech. También puede comunicarse con nuestro equipo en cualquier momento a través de la página de contacto.

¿Aún tiene dudas antes de decidirse?
- Hable con un consultor, no con un centro de llamadas
- Revise sus cifras en Smart Flow antes de decidir